Understanding SAFEs
Videos · Startups · Source
What is a SAFE?
- Simple Agreement for Future Equity
- Convertible security
- Receive money now, issue stock later
- Minimal negotiations
- You decide how much money an investor will put it, and at what negotiation cap
- Actual valuation will be decided in a priced round
- Not debt
Main SAFE structure
THIS CERTIFIES THAT in exchange for the payment by [Investor Name] (the "Investor") of $[______________] (the "Purchase Amount") on or about [Date of Safe], [Company Name], a [State of Incorporation] corporation (the "Company"), issues to the investor the right to certain shares of the Company's capital stock, subject to the terms described below
This Safe is one of the forms available at https://ycombinator.com/documents, and the Company and Investor agree that neither one has modified the form, except to fill in blanks and bracketed terms
The "Valuation Cap" is $[_________________]. See Section 2 for certain additional defined terms.
Anatomy of the SAFE
5 pages in length. Split into 5 sections
- Section 1 - Events
- Equity financing (company raising money)
- Liquidity event (company selling)
- Dissolution (company closed down)
- Liquidation priority (who comes first in the queue to be repaid)
- Termination
- Section 2 – Definitions
- Section 3 – company representations
- Section 4 – investor representations
- Section 5 – legal boilerplate language
Post-Money safes
Pre-money valuation + money raised = post-money valuation
To understand how much of the company is sold:
- Founder Ownership = Amount raised / Post-money valuation cap
Different flavors of the SAFE
- Capped (valuation is capped)
- Discount (you get a %discount on the valuation)
- Uncapped (extremely uncommon)
- Uncapped with a "most favored nation" clause (can happen if you're raising money early on — but very uncommon too)
Dilution
Assume that – at incorporation – you just have two founders who have split up the equity equally
Next, they raise some money as Post-money safes from two different investors in two different rounds
Investor A:
- $200k, $4M post-money valuation cap
- Ownership = $200k/$4M = 5%
Investor B:
- $800k, $8M post-money valuation cap
- Ownership = $800k/$8M = 10%
Dilution for founders = 5% + 10% = 15%
When you raise some cash, you'll probably hire people. When this happens, you'll also likely issue stock + set aside an option pool. Founders will get diluted when this happens. Let's assume that the total number of shares (common shares) are 10,000,000 at this stage
A year after this, you'll have a priced round. Let's say you raise $5M ($4M from the lead investor) at a $15M pre-money valuation for your Series A. So your post-money valuation is $20M, and the target available option pool is 10% of the post-money valuation
In the priced round, 3 things happen:
- Safes convert as shares – note that safes are included in the pre-money valuation!
- Optional pool is increased
- New investors invest
Step 1.
When the safes convert, new shares are first issued to the SAFE investors
Since they have 15% of the company (pre-money), they get an additional 1,764,705 shares (the founders 10M shares stay – dilution comes from the issuing of new shares)
- this is transitory. cap-table won't look this this. it's just a step in the calculation
If you raise at a post-money valuation that is lower than the SAFE cap, early investors will have a higher ownership than the 15% at this stage. This is why you shouldn't negotiate a crazy high valuation when getting SAFEs
Step 2.
Option pool increases
In this case, 1.695M additional shares are issued since the target available optional pool is 10% post money and the post-money valuation is $20M
Step 3.
New money invests
- Price per share = Pre-Money Valuation / Capitalization
- Capitalization = Total fully diluted shares after safe conversion and option pool increase
- Number of shares that Series A investors get = investment amount / price per share
In this case, new money capitalization = 10M original shares + 1.76M safe investor shares + 1.695M option pool increase shares = 13.455M
New money price = $15M / 13.455M shares = $1.114
Total new money shares = $5M / $1.114 = 4.48M shares
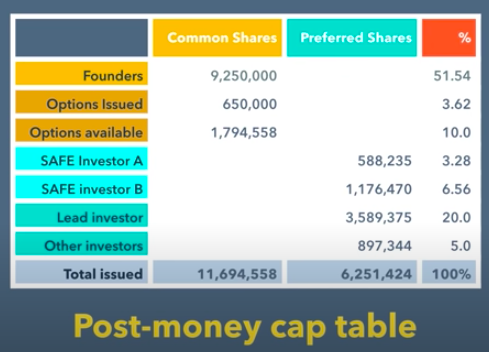
This is the post money cap table
Other related topics
Safes vs convertible debt
- Safes aren't debt
- Convertible debt is more complex – maturity, interest rates etc
- Try not to have a combination of the two
Post-money safes are recommendeed
- Pre-money safes are an option, but it's much harder to calculate dilution (specially wrt the increase in option pool)
Don't over-optimize on market caps
- really doesn't matter all that much in terms of dilution
- In this example, if founders had negotiated for $800k on a $10M post-money safe instead of $8M, they would've owned 52.77% instead of 51.54%