Narrative and Numbers, Aswath Damodaran
Books · Investing · Source
Summary
Clear, well-written book that talks about how stories and business fundamentals shape valuation. I read as I was also reading Poor Charlie’s Almanac, and hoped to get a better grip on how to value companies.
Why both storytelling and numbers are important
The first third of the book is about why both storytelling (narrative) and numbers are important when valuing an asset:
- To be a successful business, not only do you have to build a better mousetrap, but you have to tell a compelling story about why that mousetrap will conquer the business world to investors (to raise capital), to customers (to induce purchases), and to employees (to get them to work for you)
- But storytelling that is not bounded by numbers can quickly devolve into fantasy land. Understand if a story is possible, whether it is plausible, and how probable it is. Numbers are a great way to figure this out
- This should be the golden age for numbers, more data and better analytics tools. But this surge in number-crunching and computing powers that has created a greater demand for good storytelling, often as a counterpoint to masses of numbers
- If you rely only on numbers, you can suffer from the illusion of precision (estimates are treated as facts, often leading to disastrous consequences), the illusion of objectivity (the map is not the terrain), and the Lemming Problem (if the future is going to be different from the past, the predictions based upon past data will come apart)
The classic story models, and how stories go awry
Many stories are just a simplified version of the classic Hero's journey (outline below) – but some are different
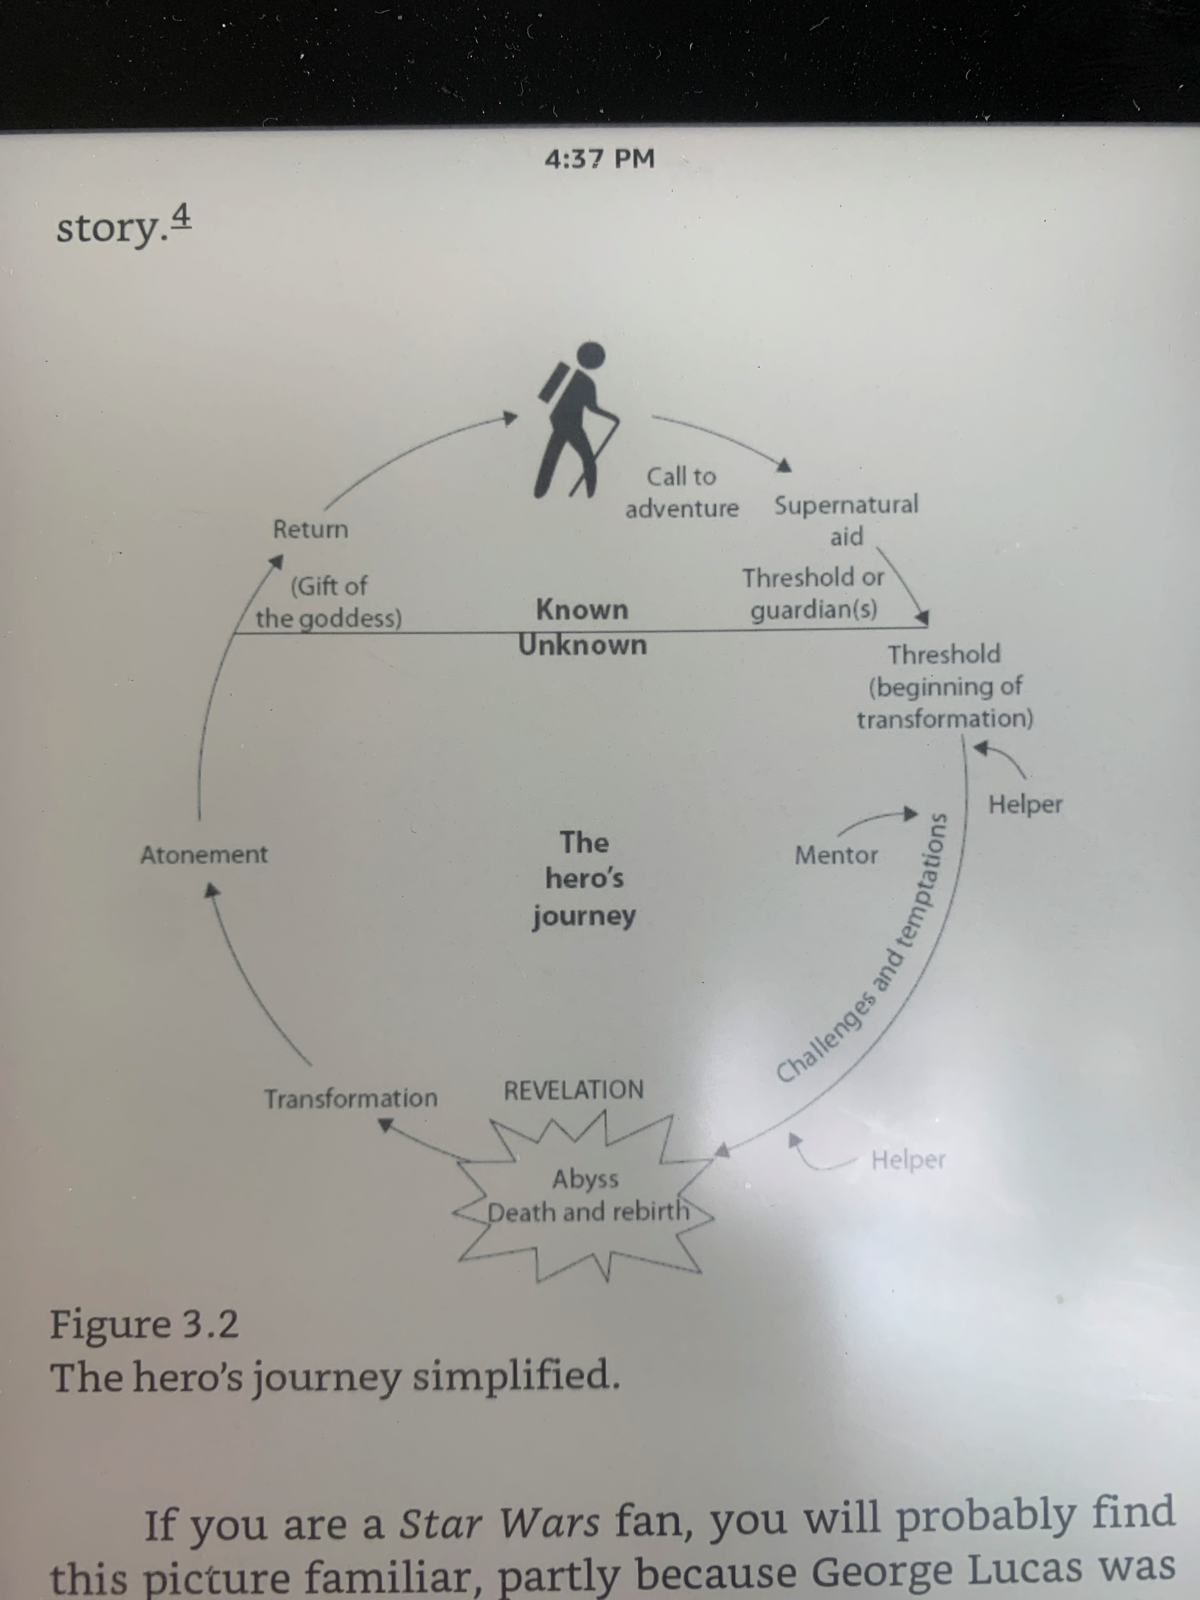
Other stories include:
- The bully: Company with a large market share, a superior brand name, access to lots of capital, and a reputation for ruthlessness. They will steamroll competition to deliver ever-increasing revenues and profits
- The Eureka moment: Company that claims to have found an unmet need in the market, usually in a serendipitous way, and then has come up with a way of meeting that need
- The better mousetrap: Company that contends it has a better way of delivering an existing product or service that will be more desirable and better suited to the need. They will eat into the market share of the existing players in the market
- The disruptor: Company that changes the way a business is run, altering fundamental ways in which the product or service is delivered. The status quo is ineffective and inefficient, and disruption will change the business (while making money).
Stories can often go awry. Examples are:
- Assuming you are the only one with insights: it is easy to assume that while the rest of the world stays still, your company will move quickly from opportunity to opportunity – but that assumption is usually unrealistic. When you see large market opportunities, rest assured that much of the rest of the world does as well, and when you move decisively to take advantage of them, be ready for others to be making the same moves
- It is very difficult to disrupt businesses that are being run efficiently. Not only will these established companies be better positioned to push back against disruption, but customers will be less likely to shift. If a business is badly run, insofar as the players in the business make little or no money while delivering products and services that leave their customers dissatisfied, you have the perfect storm for disruption
- Stories that assume a high perpetual growth rate (any perpetual growth rate that exceeds the nominal growth rate of the economy is impossible – as the company will then be bigger than the economy)
- Bigger than the market: your market share can never be more than 100%
- Claiming that you can simultaneously capture market share and raise prices in a competitive market
- Big market delusion: a high growth story that’s plausible at the individual company level can become implausible in the aggregate — this is what leads to funding bubbles
What determines value?
This discusses the differences between pricing and valuation – and is the bit I found most valuable.
- The value of a business is determined by the magnitude of its cash flows, the risk/uncertainty of these cash flows, and the expected level and efficiency of the growth that the business will deliver. But the price of a traded asset (stock) is set by demand and supply. While the value of the business may be one input into the process, it is one of many forces. The push and pull of the market (momentums, fads, and other pricing forces) and liquidity (or the lack thereof) can cause prices to have a dynamic entirely their own, which can lead to the market price being different from value.
- In pricing, you find comparable assets in the market, look for pricing metrics that investors use in pricing these assets, and then price your asset accordingly. This can be the wrong approach if your asset has attributes that are markedly different from that of “comparable” assets
- Damodaran then gives examples of how he valued businesses in 2014 and 2015, and outlines his process in great detail. What’s fascinating is that he undervalued almost all businesses (specially tech businesses). He believed in the wrong stories (for example, not anticipating how big the online advertising industry would become or how Uber would branch out into food delivery). But the book, generally speaking, still has a lot of value
Summary
The book will help anyone who is trying to evaluate stories that value a business – from a startup founder to a public market investor. Damodaran’s process – while clearly not bulletproof – is a phenomenally structured and debuggable way to value a business, and will be a great addition to other models (mental or spreadsheet) that you use
Highlights (raw highlights from book — most people should stop reading here)
Stories
a valuation that is not backed up by a story is both soulless and untrustworthy. we remember stories better than spreadsheets.
let’s assume that I showed you a valuation of Ferrari, the legendary luxury auto company, at the time of its initial public offering. Let’s assume that this valuation takes the form of a spreadsheet with forecasted revenues, operating income, and cash flows and that the key assumptions are presented as numbers. I tell you that I expect Ferrari’s revenues to grow 4 percent a year for the next five years, before dropping down to the growth rate of the economy; that the pretax operating margin will be 18.2 percent; and that the company will be able to generate €1.42 in revenues for every €1 it invests in the business. If you are not a numbers person, you are probably already lost, and even if you are, it is unlikely that you will remember the numbers for long.
Consider an alternative. I could tell you that I see Ferrari as a maker of luxury automobiles that can charge astronomically high prices for its cars and earn huge profit margins because it keeps its cars scarce and available only to an exclusive club of the very wealthy. That story is more likely to be remembered, but without specifics, it tells you little about how much you should be willing to pay for the company.
There is a third option, where I tie the low revenue growth (4 percent) to Ferrari’s need to maintain its exclusivity, with that same exclusivity allowing it to generate its huge profit margins and maintain stable earnings over time, since those who buy Ferraris are so wealthy they are unaffected by the ebbs and flows of the economy that affect other automakers. By tying my numbers to a story about the company, I not only ground my numbers but also provide a forum for you to offer your own story for Ferrari, which will then yield a different set of numbers and a different value for the company. That, in a nutshell, is the endgame for this book.
For the storytellers, it is easy to wander into fantasyland, where the line between good stories and fairy tales gets crossed. That may not be a problem if you are a novelist, but it can be a recipe for disaster if you are building a business.
Since stories tend to appeal to the emotions rather than to reason, they also play on our irrationalities, leading us to do things that do not make sense but feel good, at least when we do them. In fact, as con men through the ages have discovered, nothing sells better than a good story.
good storytelling can make a huge difference in the success of a business, especially early in its life. To be a successful business, not only do you have to build a better mousetrap, but you have to tell a compelling story about why that mousetrap will conquer the business world to investors (to raise capital), to customers (to induce purchases), and to employees (to get them to work for you).
storytelling in business comes with more constraints than storytelling in novels, since you are measured not just on creativity but on being able to deliver on your promises. The real world is very much a part of your story, and much as you would like to control it, you cannot.
Numbers
With computerized databases and computational tools becoming available to the masses, the data world is getting “flatter” and more democratic, allowing us all to play number-crunching games that we could never have tried a few decades ago.
Two real-world developments, huge databases that can be accessed instantaneously and powerful tools to work with that data, have tilted the balance in almost every endeavor, but particularly so in financial markets, toward numbers.
These developments have come with a cost, which is that the problem that you face in investing now is not that you don’t have enough data but that you have too much, often pulling you in different directions.
you follow simple rules in collecting data, including judgments on how much data and over what time period, and look for ways to avoid or at least minimize the biases that can find their way into that data.
use basic statistics to make sense of large and contradictory data and statistical tools to fight data overload.
you have to come up with interesting and innovative ways of presenting the data to make them understandable to those who might not grasp the statistical nuances.
We relate to and remember stories better than we do numbers, but storytelling can lead us into fantasyland quickly,
Numbers allow us to be disciplined in our assessments, but without stories behind them, they become weapons of intimidation and bias rather than discipline.
You need to bring both stories and numbers into play in investing and business, and valuation is the bridge between the two,
Big Picture Process
You begin by understanding the company you are valuing, looking at its history, the business it operates in, and the competition, both current and potential, it may face. You then have to introduce discipline into your storytelling by subjecting your story to what I call the 3P test, starting with the question of whether your story is possible, a minimal test that most stories should meet; moving on to whether it is plausible, a tougher test to overcome; and closing with whether it is probable, the most stringent of the tests.
If you tell good stories, it is natural to get attached to them and to view any questioning of those stories as an affront. While it is good to be able to defend your stories against challenges, it is also important to keep the feedback loop open, listening to comments, questions, and critiques and using them to modify, adapt, or change your story lines.
the story itself will change over time. Some of this change will be the result of macroeconomic shifts, as interest rates, inflation, and the economy map out their own paths. Some will be the result of competitive dynamics, as new competitors enter, old competitors modify their strategies, and some competitors drop out of the market the company is targeting. Some story shifts can be traced to changes in management, both in terms of personnel and tactics. The bottom line is that it is hubris in storytelling (and the number crunching that emerges from it) to assume that the story you tell will remain immune from the real world.
three groups of how stories change: narrative breaks, in which real-life events decimate or end a story; narrative changes, in which actions or outcomes lead you to alter the story that you are telling in fundamental ways; and narrative shifts, in which occurrences on the ground don’t change the basic story but do alter some of its details in good or bad ways.
what are the causes of narrative alterations? The first is news stories about the company, some emanating from the company and some from outsiders (regulators, analysts, journalists) who track the company.
Thus, every earnings report from a company, to me, is an occasion for me to reexamine my story for that company and tweak it or change it significantly, depending on the content. Management retirements (forced or voluntary), corporate scandals, and activist investors buying shares in the company can all lead to narrative reassessments.
An acquisition announcement, a stock buyback, or increasing or ceasing to pay dividends can also fundamentally change how you look at a company. The second cause is macroeconomic stories, wherein changes in interest rates, inflation, commodity prices, or even political upheavals can lead you to change the way you think about an individual company’s prospects and value.
you are an investor who likes stability in your stories (and in value), you will be uncomfortable making the changes the real world thrusts upon you, and you can react in one of two ways. The first is to restrict your investing to companies with established business models in stable markets, where your story does not change over time, and that is the path that many old-time value investors have chosen to take, pointing to the history of success that others who have taken this path have had in the past.
The other is to learn to live with the discomfort of change and to accept that not only is it unavoidable but that the biggest business and investment opportunities exist in those environments where there is the most change. One reason that I am increasingly attracted to the storytelling aspect of valuation is because I have chosen the second path.
you cannot value companies prone to change using just equations and models; you also need a narrative that you can go back to when the numbers are in flux.
Businesses age, much like individuals, with big differences across companies in the aging process. I present my vision of the life of a business in figure 1.3.
Early in the life cycle, when a business is young, unformed, and has little history, its value is driven primarily by narrative, with wide differences across investors and over time. As a company ages and develops a history, the numbers start to play a bigger role in value, and the differences across investors and over time start to narrow.
This should be the golden age for numbers, with increased access to immense amounts of data (big data) and improved data-analytic tools and machine power, and as we will see in the next chapter, there are signs that it is. Ironically, though, it is exactly this surge in number-crunching and computing powers that has created a greater demand for good storytelling, often as a counterpoint to masses of numbers.
storytelling left unchecked can easily lose focus, and in the context of business stories, that can be dangerous for everyone involved.
Bernie Madoff pitched an investment scheme in which he claimed he would buy about fifty of the hundred largest market cap stocks, timing his buys “opportunistically” (leaving investors with the impression that he had found a way to time markets well) and then using put options to limit potential losses. The key selling ingredients were threefold. The first was that the strategy was “too complicated for outsiders to understand” and too proprietary to be described in detail. The second was that it was supposedly so well designed that it would never lose money, even in bad months for the market. The third, and perhaps cleverest component, was that the strategy would make moderate rather than exceptionally high returns.
From the outside, the Theranos path to disrupting the blood-testing business seemed smooth. The company continued to trumpet its claim that the drop of blood in the Nanotainer could run thirty lab tests and deliver them efficiently to doctors, going so far as to list prices on its website for each test, with costs dramatically lower (by as much as 90 percent) than the status quo.
disruption seemed imminent. The Theranos story started to come apart on October 16, 2015, when a Wall Street Journal article reported that the company was exaggerating the potential of the Nanotainer and that it was not using the Nanotainer for the bulk of the blood tests it was running in-house.
article’s contention that senior lab employees at the company found that the Nanotainer’s blood test results were not reliable, casting doubt on the science behind the product.
It was reported that the Food and Drug Administration, after an inspection at Theranos, had asked the company to stop using the Nanotainer on all but one blood test (for herpes) because the FDA had concerns about the data the company had supplied and the product’s reliability.
GlaxoSmithKline, which Holmes claimed had used the product, asserted that it had not done business with the start-up for the previous two years, and the Cleveland Clinic also backed away from its adoption.
was not until October 27, 2015 that Holmes finally agreed that presenting the data that the Nanotainer worked as a reliable blood-testing device would be the most “powerful thing” that the company could do. In the months following, the setbacks continued, as more evidence emerged of problems in the company’s labs and with the blood testing technology. By July 2016, the company’s future looked bleak as the FDA proposed a ban on Ms. Holmes from operating labs, and business partners (like Walgreens) abandoned the company.
If a Hollywood screenwriter were writing a movie about a young start-up, it would be almost impossible to come up with one as gripping as the Theranos story: a nineteen-year-old woman (that already makes it different from the typical start-up founder) drops out of Stanford (the new Harvard) and disrupts a business that makes us go through a health ritual we all dislike.
To add to its allure, the story had a missionary component to it of a product that would change health care around the world by bringing cheap and speedy blood testing to the vast multitudes who cannot afford the status quo. The mix of exuberance, passion, and missionary zeal that animated the company came through both in speeches by and interviews with Holmes.
With a story this good and a heroine this likable, would you want to be the Grinch raising mundane questions about whether the product actually works?
five key ingredients of classical storytelling:
- Exposition or the inciting moment: This is an event that gets the story started and introduces the main problem it will be addressing.
- Complication or rising action: This is the phase in which the tension builds up in the story through additional events. In a tragedy, this is often the phase in which things are going well for the protagonist(s), and in a story with a happy ending, it is the interval of trying events
- Climax or turning point: This is the event that turns the tide, from good to bad in a tragedy and from bad to good in a happy ending story
- Reversal or falling action: In this phase, events occur that bring out the effects of the change initiated in the previous step
- Denouement: The story ends in catastrophe, if it is a tragedy, or in a resolution of some sort that shows the protagonist either winning or losing.
The Freytag storytelling structure is one in which the narrator controls the environment, acting as stage master who determines when surprises happen, to whom, and with what consequences. Thus, its direct use in business storytelling is limited, since so much of what happens is out of your control, your best-planned story can be rendered to waste by a real-world surprise, and the ending is not yours to script.
Like the hero in Campbell’s structure, Steve’s call to adventure was in a garage in Silicon Valley where he and Steve Wosniak built the first Apple computer, and his challenges and temptations as he went on to make Apple a succesful company are well chronicled. It was, however, his ouster from Apple and his subsequent return (his death and rebirth) that set the stage for one of the greatest second acts in corporate history.
In his book on storytelling, Christopher Booker contends that there are only seven basic plots for stories
In the first one, overcoming the monster, you have the underdog, usually smaller and perceived to be weaker, beating out an evil adversary.
A rebirth is a story of renewal, in which a person is reborn to live a better life.
In a quest, the protagonist goes on a mission to find an item or thing that will save him or her and perhaps the world.
A rags-to-riches story is about transformation, with someone or something who is poor and weak rising to become wealthy and powerful.
In a voyage and return, the characters embark either intentionally or accidentally on a journey of discovery that ends with them returning, usually wiser, happier, or richer, to their point of origin.
In comedy the intent is to make you laugh with the players or at them as they stumble through life’s challenges, and in a tragedy you get the flip side: the objective here is to make you cry.
With young start-ups in particular, and even with some established businesses, the story of the business can be tightly tied to the story of the founder, and it is the founder’s story that draws investors to the business.
Business stories
1. The Horatio Alger story: This is a classic, especially in the United States, and it is a variant of the rags-to-riches story. Investors are attracted to this story by the tenacity of the founder in making something of himself or herself in the face of immense odds.
2. The charisma story: In this narrative the founder’s story is built around an epiphany, a moment when he or she gets a vision of business opportunity and then proceeds to fulfill that vision. Elon Musk has founded or cofounded many businesses, including SpaceX, Tesla, and SolarCity, but with each of these businesses, investors are as much drawn to him, as a charismatic founder, as they are to the companies themselves.
3. The connections story: In some businesses, it is who you know that gives you the advantage, and founders who have the right connections, either because of family background or due to their past roles as politicians or regulators, are given special deference.
4. The celebrity story: Investors are sometimes drawn to the celebrity status of a founder, in the belief this status will allow them to attract business and generate value. Jack Nicklaus, Magic Johnson, and Oprah Winfrey have all used their celebrity status to build successful businesses, with many investors being drawn to the celebrities’ names as much as to the businesses themselves.
5. The experience story: It is the track record of some founders that draws investors to their businesses. The assumption, when investing in these businesses, is that if they have been successful in the past in building businesses, they will be successful in their new ventures.
There are two dangers of crossing the line and making a business story all about the founder or founders. First, a business that is too closely tied to its founder may not be able to survive personal failures on his or her part. When Martha Stewart was convicted of insider trading in 2003, the publicly traded company that shared her name suffered mightily in the aftermath, dropping almost 15 percent on her indictment.
Second, while listeners are always attracted by the personal aspect of founder stories, these personal elements still have to be connected to business success. That perhaps explains why so many celebrities start off on the road to entrepreneurship and so few make it through successfully. CASE
Business stories can range across the spectrum, and the one you use will depend on where the business is in the corporate life cycle and what the competition it is facing looks like. Again, at the risk of both overgeneralizing and not spanning the spectrum of possible stories, a few classic business stories are presented in table 3.1.
Classical business stories
The bully
- Company with a large market share, a superior brand name, access to lots of capital, and a reputation for ruthlessness. They will steamroll competition to deliver ever-increasing revenues and profits.
The underdog
- Company that is a distant second (or lower) in market share in a business, with claims to a better or cheaper product than the dominant company
- They will work harder than the dominant player at pleasing customers, perhaps with a kinder, gentler corporate image.
The eureka moment
- Company that claims to have found an unmet need in the market, usually in a serendipitous way, and then has come up with a way of meeting that need
- They will succeed as a business by filling the unmet need.
The better mousetrap
- Company that contends it has a better way of delivering an existing product or service that will be more desirable and better suited to the need
- They will eat into the market share of the existing players in the market
The disruptor
- Company that changes the way a business is run, altering fundamental ways in which the product or service is delivered
- The status quo is ineffective and inefficient, and disruption will change the business (while making money).
The low-cost player Company that has found a way to reduce the cost of doing business and is willing to cut prices on the expectation that it can sell a lot more Increased sales will more than make up for lower margins.
The missionary Company that presents itself as having a larger, more noble mission than just making money They will make money while doing good (for society).
it is possible for a company to have dual narratives, as is the case with Uber in September 2015, a company that is telling both a disruption story (it is changing the car service business) and a dominance story (it is presenting itself as unstoppable in the ride-sharing market).
as a company moves through the life cycle, its narrative will change. Thus, when Google entered the search engine market in 1998, it was the scrappy underdog to the established players, but by 2015 it had made the transition to being the dominant player in the market, perhaps even a bully,
here are the steps you can adopt to tell a better story.
1. Understand your business and know yourself: As a storyteller, it is difficult to tell a story about a business if you don’t understand the business yourself. If your vision for the business in terms of what it does and where you see it going in the future is fuzzy or unformed, your story about it will reflect that confusion.
2. Understand your audience: Your business story may not be the same when you are talking to different stakeholders (employees, customers, or potential investors), because each has a different interest in the story. While employees may share your enthusiasm for the success of the business, they are just as interested or perhaps more so in how you plan to share that success with them and the personal risks they face from failure. Customers are more interested in your products than in your profits and want to hear the part of your story in which you explain how your product or service will meet their needs and what they will have to pay in return.
3. Marshal the facts: Nothing will undercut your story more than mangling the facts. Thus, it will behoove you to do your homework on your company, its competitions, and the market you are trying to capture. To check your story before delivering it, you should consider adapting the five Ws of journalism to business: • Who are your customers, your competitors, your employees? • What does your business look like now and what is your vision for what it will look like in the future? • When or over what time period do you see your business evolving to match your vision? • Where (in terms of markets and geographies) do you see yourself operating? • Why do you see yourself as the winner in this market?
4. Talk in specifics: While your business story may be built around market opportunities or macroeconomic trends, you will need to be specific about how you plan to take advantage of these trends. Assume, for instance, that you are building a social media company. It is not enough, for instance, to argue that people are increasingly turning to social media to interact, to get their news, and even for entertainment. You need to specify what you are offering as a company that will draw these people to your products or services.
5. Show, don’t tell: Steve Jobs’s keynote speeches for Apple resonated because he was willing and eager to share Apple’s new products on the stage, even at the risk of having some of them malfunction. In the same vein, being able to show how your products and services work can make your business story not only more memorable but also more effective.
6. Have a good ending: Taking Aristotle’s advice to heart, you should craft an ending for your story that not only leaves your audience excited and eager to act but also encapsulates the message you were trying to deliver.
The Ingredients in a Good Story
1. The story is simple. Good business stories have a core message they deliver without distractions and eliminate complexities and complications that get in the way of that message.
2. The story is credible. A good story, in business, has to be actionable and deliverable, and consequently needs to meet the reality test. That may mean being open about your limitations as a business, while presenting the strengths that you bring to the game.
3. The story is authentic. Authentic is a much used word, with nebulous meaning, but it is undeniable that your stories resonate more when they reflect who you are as a person and what your business is truly
4. The story is emotional. I don’t mean emotional in the sense that the storyteller cries on the stage, but emotional in the sense that it comes from the heart.
The power of numbers in investing is best seen in the growth of quant investing, whose promoters are open about the fact that their investing is based only on the numbers. In fact they compete with one another in explaining how much they have turned their investment processes over to the data and the power of their data-analytic tools.
The Markowitz revolution that gave birth to modern portfolio theory also was a contributor to quant investing. The approach to finding efficient portfolios, that is, portfolios that delivered the highest returns for a given level of risk, that Harry Markowitz developed in the 1950s, was a computational nightmare at that time, given the limitations of both data access and analysis. Today it is possible for an individual investor, armed with a personal computer and online data, to generate efficient portfolios on stock samples that would have taken weeks to create a few decades ago.
The Dangers of Numbers and The Illusion of Precision: estimates are treated as facts, often leading to disastrous consequences.
One of the key findings in behavioral economics is that our response to numbers depends not only on their magnitude but also on how they are framed. That is the weakness that retailers exploit when they mark up the price on an item to $2.50 and take 20 percent off, since shoppers seem more inclined to buy that item than a similar one priced at $2.00.
Given that the equity risk premium is a key input for both corporate finance and valuation, how can you estimate this number? Most practitioners turn to history, looking at what investors have earned in the past on stocks relative to a riskless investment.
Probing that number a little more, it should be noted that this average comes from stock returns that are volatile, with returns ranging from a high of almost 50 percent in 1933 to a low of close to −44 percent in 1931.
The Illusion of Objectivity & The Illusion of Control: Measuring something does not mean that you are controlling it. Just as a thermometer can tell you that you have a fever but cannot treat it, measuring the standard deviation of a portfolio only tells you that it is risky but does not protect you from that risk.
valuation, areas in which I spend most of my time, I notice this phenomenon play out in many places. The first is in the use of what if or sensitivity analysis, often as an addendum to a valuation or a project analysis. In most cases, these analyses happen after the decision has already been made, and the only explanation I can provide for why analysts spend so much time on them is that it makes them feel more in control.
The second is in the attention that analysts give to small and often irrelevant details. I say, only half jokingly, that when in doubt, I add decimals to my final numbers, whether they be valuations of companies or rates of return for projects.
The danger with deluding yourself that you are in control, just because you have a sophisticated measurement tool, is that you may not only let the numbers overwhelm your common sense but that you will not prepare yourself properly for the dangers ahead.
That, unfortunately, was what happened at banks around the world during the banking crisis in 2008. In the two decades prior to the crisis, these banks had developed a risk measure called “value at risk” (VAR), which allowed them to see in numerical terms their worst-case scenarios in terms of losses from their businesses.
In the intervening period, risk-management experts and academics refined VAR to make it more powerful and more complex, with the stated intent of making it more effective. As bank managers became increasingly reliant on VAR, they also let down their guards and concluded that if the computed VAR was within their defined safe limits, their risk taking was also under control.
As the funds at their disposal got larger, the firm had to widen its search to include riskier investments, though it did find those investments by analyzing the data. By itself, this would not have been fatal, but the firm continued to use the same leverage on these riskier investments as it did on its safe investments. It did so because the complex models it had built told it that while the individual investments were risky, based on their history, they would not move together and that the portfolio was therefore a safe one.
In 1997, the strategy unraveled as collapses in one market (Russia) spread into other markets as well. As the portfolio dropped in value, LTCM found itself facing the downside of its size and high leverage.
Unable to unwind its large positions without affecting market prices and facing the pressures of lenders, LTCM faced certain bankruptcy. Fearing that it would bring down other investors in the market, the Federal Reserve engineered a bank-led bailout of the firm.
The Intimidation Factor If you are a corporate financial analyst, a consultant, or a banker facing a skeptical audience, one simple technique to silence the room is to open up a complex spreadsheet filled with numbers. This works particularly well if your audience is not comfortable with numbers, but even if you have a numerically literate audience, the human mind is generally incapable of looking at a
The Intimidation Factor If you are a corporate financial analyst, a consultant, or a banker facing a skeptical audience, one simple technique to silence the room is to open up a complex spreadsheet filled with numbers. This works particularly well if your audience is not comfortable with numbers, but even if you have a numerically literate audience, the human mind is generally incapable of looking at a hundred numbers on a page and making sense of them.
that intimidation works at cutting off debate and preventing probing questions that may uncover large and potentially fatal weaknesses embedded in the numbers.
If the numbers are all that drive your decisions, as some purist number crunchers claim, you are in big trouble as the decision maker, for two reasons. The first is that you have positioned yourself perfectly for being outsourced, replaced not just by a cheaper number cruncher in a different location but by a machine.
If your defense against the outsourcing is that you have better data and more powerful computers than most other people, you open yourself up to a second problem, which is that a purely number-driven decision process is easy to imitate.
The Lemming Problem
Let’s assume that you live in big data heaven, where you and everyone else has huge databases and powerful computers to analyze and make sense of the data. Since you all share the same data, and perhaps even use the same tools, you are going to highlight the same opportunities, generally at about the same time, and seek them out for profit. That process is going to create “herding,” when you buy and sell the same stocks at the same time. So what? That herding will create momentum, which will reinforce your decisions at least in the short term but will also cause you to be collectively wrong if there is a structural shift in the underlying process (business, market, or economy).
The data, after all, comes from the past, and if the future is going to be different from the past, the consequence of the structural shift, the predictions based upon the data will come apart. The implications are sobering. As we move increasingly to a data-driven world, and more and more people have access to that data, it stands to reason that we will see more booms and busts than we have historically. Bubbles in markets will be bigger than they used to be and when these bubbles burst, as they inevitably will, the carnage is going to be greater as well.
Storytelling as Antidote
First, the nature of stories is that they are fuzzy and remind us that precise as the numbers look, changing your story will change the numbers. Second, that recognition also will dispel the notion that you somehow can deliver the numbers you have forecast, since stories can be changed by forces out of your control. Third, when you are forced to unveil the story that backs your numbers, your biases are visible not just to the rest of the world but to yourself.
the capacity to combine stories with numbers makes it more difficult for others to imitate you, if you are successful. Unlike models that can be easily copied, storytelling is more nuanced, personal, and difficult to replicate.
The one problem that adding stories to numbers will not solve, at least in the near term, is herding. The groupthink that leads people to pile into the same stocks and investments because the numbers lead them there will also lead to them to reinforce one another’s stories.
There is an argument to be made, though, that the best way to break the madness of crowds is with a combination of an alternative (and more realistic) story, backed up by numbers to give it credibility.
I am not ready to bury quant investing yet, since the forces that brought it to the forefront are still around us, but I think that its successes and failures reveal both the promise and peril of numbers. Quant investing, to succeed and prosper, has to find a place for storytelling and narrative in conjunction with the numbers, and if it does, it will not only be more successful but it will also be more difficult to imitate and outsource.
The proliferation of data has also meant that not only do we have far more data to process but that data can offer contradictory signals, making it more difficult to convert it into information. Thus, it is data overload that we face, not information overload.
There are three steps in the data-to-information process,
1. Data collection: The first step is collecting the data. In some cases, this can be as simple as accessing a computerized database. In others, it will require running experiments or surveys.
2. Data analysis: Once the data has been collected, not only does it have to be summarized and described, but you have to look for relationships in the data that you can use in your decision making. It is at this stage that statistical analysis comes into play.
3. Presentation: Having analyzed the data, you have to present it, not only so others can see and use the information you have gleaned from the data, but so you yourself have a sense of what that information is.
Collecting Data
data can either come from records maintained by an organizing entity (government, security exchange, regulator, private business), from surveys, or from experiments. As more and more of our transactions are done on or with computers, the data is generally recorded online, making the job of creating and maintaining databases simpler.
1. Public company versus private company data: Publicly traded companies in most of the world face information disclosure requirements; they have to make their financial statements available to the public. As a consequence, it is far easier to access data on public companies than their privately owned counterparts.
2. Accounting versus market data: With public companies, not only do you have access to financial statement data but you also can obtain data from financial markets on price movements and transactions data (bid-ask spread, trading volume).
3. Domestic versus global data: Many researchers, and especially those in the United States, tend to stay focused on U.S. data, partly because they trust and understand it more and partly because it is easier to access, for most of them. As both companies and investors globalize, that domestic focus may no longer be appropriate, especially if the decisions you are making have global consequences.
4. Quantitative versus qualitative data: Databases tend to be skewed heavily toward quantitative data, partly because that is the bulk of the data collected and partly because it is so much easier to store and retrieve than qualitative data. Consequently, it is easy to obtain data on the number of directors at each publicly traded company but much more difficult to get data on how much dissension there is at board meetings at companies. One of the outgrowths of the surge in social media sites is the development of more sophisticated techniques for reading, analyzing, and storing qualitative data.
Data-Collection Biases For those who still hold onto the belief that data is objective, a closer look at the data-collection process is often all that is needed to dispel that belief.
SELECTION BIAS
SURVIVOR BIAS
NOISE AND ERROR
data input errors,
missing data,
One solution is to eliminate observations with missing data, but not only will this reduce your sample size, it may introduce bias if missing data is more common in some subsets of the population than in others.
Biases in Analysis
1. We put too much trust in the average: With all of the data and analytical tools at our disposal, you would not expect this, but a substantial proportion of business and investment decisions are still based on the average. I see investors and analysts contending that a stock is cheap because it trades at a PE that is lower than the sector average or that a company has too much debt because its debt ratio is higher than the average for the market.
2. Normality is not the norm: One of the shameful legacies of statistics classes is that the only distribution most of us remember is the normal distribution.
3. The outlier problem: The problem with outliers is that they make your findings weaker. Not surprisingly, the way researchers respond to outliers is by ridding themselves of the source of the trouble.
which may diverge from the founder’s story. In my view, a good business story, that is, one that has staying power and backs up a successful business, is one in which listener and storyteller interests converge.
you are a potential investor in a publicly traded company, you often have to be both a storyteller, developing a narrative that underpins value, and a listener, probing your own story for its weakest links.
a business narrative needs the following ingredients to work:
1. It has to be simple: A simple story that makes sense will leave a more lasting impression than a complex story in which it is tough to make connections.
2. It has to be credible: Business stories need to be credible for investors to act on them. If you are a skillful enough storyteller you may be able to get away with leaving unexplained loose ends, but those loose ends will eventually imperil your story and perhaps your business.
3. It has to inspire: Ultimately, you don’t tell a business story to win creativity awards but to inspire your audience (employees, customers, and potential investors) to buy into the story.
4. It should lead to action: Once your audience buys into your story, you want them to act, employees by choosing to come to work for your company, customers by buying your products and services, and investors by putting their money in your business.
bottom line for a business narrative is that it is less about specifics and details and more about big picture and vision.
The Pre-work Before a story is constructed for a business, there is homework to be done by both storytellers and listeners. You have to review the history of the business for which you are telling the story, understand the market in which the company operates, and have a measure of what the competition looks like. The
If the company has been in operation for a while, you can start with its history, trying to get measures of past growth, profitability, and business direction. While you may not be bound by that history in constructing your narrative for the company’s future, you still have to be aware of the past.
With young companies, there will be less to learn from examining the past. Poring over the financial statements for a young start-up will usually yield the unsurprising conclusion that it did not generate much (if any) in revenue in the most recent periods and it reported losses while doing so. With these companies, you may learn more as an investor by looking at the founders/owners running the businesses and their histories and other more established companies in the same business.
Growth How quickly is the overall market growing? In addition to looking at the average growth rate over time, you also want to detect shifts in the market across product lines and geographies. Are some parts of the market growing faster than others?
Profitability How profitable is this business, in the aggregate? Look at profit margins (gross, operating, and net) and accounting return trends over time. Are there any trends over time in the profitability? Investing for growth What assets do companies in this business have to invest in, to grow? With manufacturing companies, investment is generally in plant, equipment, and assembly lines, but with technology and pharmaceutical companies, the investment may take the form of R&D. How much investment are companies making collectively in this business to generate their growth? How easy is it to scale up? Risk How much do revenues and earnings vary across time? Volatility in your revenues/earnings can be caused by macroeconomic variables, which can include interest rate, inflation, commodity price, and political risk, or from company-specific variables.
Profitability How profitable is this business, in the aggregate? Look at profit margins (gross, operating, and net) and accounting return trends over time. Are there any trends over time in the profitability?
Investing for growth What assets do companies in this business have to invest in, to grow? With manufacturing companies, investment is generally in plant, equipment, and assembly lines, but with technology and pharmaceutical companies, the investment may take the form of R&D. How much investment are companies making collectively in this business to generate their growth? How easy is it to scale
Risk How much do revenues and earnings vary across time? Volatility in your revenues/earnings can be caused by macroeconomic variables, which can include interest rate, inflation, commodity price, and political risk, or from company-specific variables. What are the forces that cause these operating numbers to change? How much debt (or fixed commitments) do companies in this business tend to carry? What are the risks that companies in this business may fail? What is the trigger (debt payments due or running out of cash) that cause failure?
Your job gets more difficult if you have companies in evolving or changing businesses, with that change coming from a maturing of the business, a shift in consumer behavior (as is the case with the entertainment content business as consumers shift to streaming), changes in regulatory rules/restrictions (for example, the telecommunication business after deregulation), or geographic shifts.
Perhaps the most challenging scenario is when you are trying to build a narrative for a young company in an evolving and shifting business. Thus, in valuing Twitter in 2013, I had to make a judgment about whether Twitter’s business would remain online advertising (its primary source of revenues in 2013) or whether it could leverage its user base to expand into retail or even convert to a subscription-driven model.
Growth Are there big differences in growth across companies within the business? If companies in the business are growing at different rates, you are trying to assess whether it is related to size, geography, or market segment. If there are big differences, what are the determinants of these differences?
Profitability Are there big differences in profitability across companies within the business? If there are big differences in profit margins across companies, you are looking to see what types of companies earn the most and which ones the least. If there are big differences, what are the determinants of these differences?
Investing for growth Is there a standardized investment model that is used by all companies in the market? As companies grow in this business, you are checking to see whether their investing needs decrease (economies of scale and networking benefits) or increase (with more competition). If not, are there differences in profitability and growth across companies with different models?
Risk Are there big differences in risk (earnings variability and survival) across companies within the business? You are interested in whether there are variations in risk (operating and survival) across companies, and if so, what causes those variations. If there are big differences, what are the determinants of these differences?
it is easy to assume that while the rest of the world stays still, your company will move quickly from opportunity to opportunity, blazing new trails and generating profits, but that assumption is usually unrealistic. When you see large market opportunities, rest assured that much of the rest of the world does as well, and when you move decisively to take advantage of them, be ready for others to be making the same moves.
So, what is it that makes the auto business so bad, at least collectively? Looking at the business broadly, here are three characteristics that underpin the business: 1. It is a low-growth business: The auto business is a cyclical one, with ups and downs that reflect economic cycles, but even allowing for its cyclic nature, the business is a mature one.
2. It has poor profit margins: A key point that Marchionne made about the auto business is that operating margins of companies in this business were much too slim, given their cost structures.
3. It has high reinvestment needs: The auto business has always required significant plant and equipment investments, but in recent years the growth of auto-related technology has also pushed up R&D spending at auto companies.
It is this combination of anemic revenue growth, slim margins, and increasing reinvestment that causes this business to deliver returns that are lower than its cost of
It is this combination of anemic revenue growth, slim margins, and increasing reinvestment that causes this business to deliver returns that are lower than its cost ofcapital,
Big Versus Small In a big story, you describe a business with an expansive vision that plans to be in many businesses and/or many geographic regions, whereas in a small one, your vision of the company is restricted to a specific business and/or a specific geographic area. No contest, you say? It is true that big stories create more excitement among employees and investors and may allow you to get a higher price attached to your business, especially early in the process. But big stories also create two costs. The first is that you will be drawn to be in many businesses at a time when you cannot afford to lose your focus, and that can have devastating effects on your company. The second is that you push expectations up, and if you fail to meet them, you will be punished.
Establishment Versus Disruption If you are describing a company that follows established business models, that is, the status quo, in how it operates, your story is a simple one. You will still have to find a business dimension, such as having a lower cost structure or being able to charge a price premium, where you can differentiate yourself from the competition. In contrast, a company that plans to challenge established business practices is following a disruption model. Again, which one you pick will depend on the company you are valuing and the business you are targeting.
if you follow Clayton Christensen’s adage that disruption generally comes from companies that have little to lose, you can more easily tell disruptive stories about companies early in the life cycle.
If a company already makes up a significant part of the status quo, it is very difficult to credibly make a disruption story about the company.
It is very difficult to disrupt businesses that are being run efficiently. Not only will these established companies be better positioned to push back against disruption, but customers will be less likely to shift. If a business is badly run, insofar as the players in the business make little or no money while delivering products and services that leave their customers dissatisfied, you have the perfect storm for disruption.
Going Concern Versus Finite Life One of the advantages of telling stories about publicly traded companies is that you can keep them going in perpetuity, legal entities with infinite lives.
there are times when an alternate vision may work better. If you are valuing a privately owned legal or a medical practice or a publicly traded royalty trust (where you get a share of a natural resource reserve until it is exhausted), your story should have a finite life span, and when that span is over you tie up loose ends (liquidate your assets) and end the story.
The Growth Spectrum The final choice you will face is where to put your company on the growth spectrum. With a start-up in a big market, the sky can be the limit in terms of growth, but with a declining company in a shrinking business, your narrative may very well require you to make the company smaller over time.
To get to a story for Uber, I went through a sequence of key parts of the narrative, and here were the judgments that I made on each one, at least in June 2014:
1. The business: Uber is and will remain an urban car service company. While it can expand into suburbia and into other businesses, the demand will be muted and it will not be cost-efficient for Uber to expand.
2. Market growth: Uber (and other ride-sharing services) will draw new customers into the urban car service markets, some from mass transit and some from private cars. That will push up growth in the urban car service market.
3. Networking benefits: Uber’s networking benefits will be local, that is, if Uber becomes the largest player in a particular city, it will find it easier to get even bigger in that city. However, that success will not benefit it in a different city, where a competing ride-sharing company may be the biggest player and enjoy local networking benefits of its own.
4. Competitive advantages: The decision to split the taxi receipts, 80 percent for the driver and 20 percent for the ride-sharing company, is arbitrary, but it is accepted as the standard, at least in the United States. Uber’s competitive position is strong enough that it will be able to maintain this sharing agreement and hence its pricing power.
5. Business model: Uber has a low–capital intensity model in which it does not own the cars that its service uses and has minimal infrastructure investment in the cities into which it expands. That model is assumed to be sustainable and Uber will continue with it.
6. Risk: Uber is a young company, losing money and in constant need of new capital. Its success in delivering growth and access to a healthy private capital market will keep the probability that the company will run out of money low, but it is still a business with substantial operating risk.
There are four ingredients that I see as key to Alibaba’s successful climb to the top of the Chinese online retail business. 1. Enter a growth market early and mold it to your strengths:
2. Differentiate and dominate:
3. Don’t be greedy:
4. Avoid pretense:
Alibaba does get a larger slice of the transaction revenues, because it charges a transaction fee, but it is still only 0.5 percent to 1.5 percent of revenues. While this small share may seem like a negative, it has proved to be one of Alibaba’s competitive advantages, since it has made it difficult for competitors to undercut Alibaba and offer better deals to customers and retailers.
Alibaba seems to generate these revenues with little effort (and marketing costs), and since the company does not aspire to be a technological innovator, its R&D and development costs are negligible. These factors result in the company’s most impressive statistic: in 2013 it had a pretax operating margin of almost 50 percent and a net profit margin of close to 40 percent, high by any standards.
A good business story is simple, credible, and persuasive. Telling one, though, requires that you understand both the business and the market in which it operates.
Once you have a story to tell about a company, the first test is to make sure your story is possible. As you will see later in this chapter, there are narratives that fail this very weak test, and these stories of course are destined for the business fairy-tale book.
The second test is determining whether the story you are telling is plausible, a stronger test. For a story to be plausible, you have to provide some evidence that it can happen, by pointing first to other companies that have pulled it off and then to your own history to make a case that you are similar to these successful companies.
The third and toughest test is determining whether the story you are telling is probable, and that requires that you be willing to quantify your story and make your best estimates of how your story will play out in numbers.
Much of conventional valuation is built around the probable, wherein you
formulate expected values in the form of revenues, earnings, and cash flows based upon probabilities. There is an opening for the plausible, primarily in your expected future growth rates. As for the possible, that is, things that may happen but you are so unsure that you don’t even know what those things might be, conventional valuation tends to break down and you have to draw on what are called real options models.
The lines between the possible, plausible, and probable are not always easy to draw, but one simple technique I have found useful is to think about the distinction between impossible, implausible, and improbable. Impossible and improbable are quantifiable, the first because you are assigning a zero probability to an event happening and the latter because you are attaching a probability (albeit a low one) that an event will happen.
Implausible lies in the muddled middle, since proving that it cannot happen is not feasible and attaching a probability judgment to it is just as difficult.
Old-time value investors, weaned on the dividend-based valuation models in Ben Graham’s book on security analysis1 and brought up on the adage that you only invest in the known and predictable, will invest in “highly probable” narrative companies, complaining even then that they would prefer total certainty for those companies.
More aggressive value investors may venture a little further down the probability path and invest in companies with lower probability outcomes at the right price.
Growth investors have to be more willing to bet on plausible story lines and build them into growth projections, accepting the fact that these projections come with more risk.
Later-stage venture capitalists tend to be bunched up toward the lower end of the plausibility spectrum, investing in companies that have promise and potential (another way to think of low-plausibility narratives). Early-stage venture capitalists are taking their chances on possibilities, knowing full well that only some of these possibilities will become plausible and fewer still will make it all the way to the probability end of the spectrum. Figure 7.4 captures the range of investment philosophies and where they fall in the possible to probable spectrum.
For a narrative to work, you have to find the right audience. A great pitch for a young, tech start-up with an unformed business model will fall flat, if made to a group of value investors at Omaha for the Berkshire Hathaway annual meeting, and an equally good pitch for a cash-generating, low-growth business will not be well received by venture capitalists in Silicon Valley.
The Impossible Stories
Bigger than the Economy
any perpetual growth rate that exceeds the nominal growth rate of the economy is impossible.
the expected growth rate in this model is a growth rate forever, and assuming a growth rate of 9 percent (in U.S. dollars) in perpetuity is pushing an impossible narrative. If a company grows at a 9 percent rate for a long enough period, it will become the economy, and even with the benefits of globalization, it will reach a point where it cannot grow any more.
Bigger than the Market
When companies have high growth potential, it should not be surprising to see revenues grow exponentially over time. But there is one caveat: No matter how successful you think a company will be in capturing market share, its eventual market share cannot exceed 100 percent.
you should build in the assumptions that scaling up will get more difficult as a company gets bigger and that the growth rates you use in future years will have to be lower than past growth rates. Just as a sanity check, it is also good to get a measure of the total market you are going after and the market share you are attributing to your company in future years.
More than 100 Percent Profit Margins
If you are valuing a company with strong pricing power, it is reasonable to build a narrative of high profit margins driving value. That said, those profit margins cannot exceed 100 percent, no matter how much pricing power a company has. The narratives that are most likely to violate this impossibility rule are efficiency stories, in which you argue that improving efficiency at a company (either from new processes or new management) will allow that company to deliver high growth in earnings over time, even with flat or slow-growing revenues.
Remember that as you cut costs (by becoming more efficient), your profit margins improve, and if you assume that they keep improving for very long periods, you should not be surprised to see your profit margins break through 100 percent.
Costless Capital Businesses need capital to grow, and those who supply capital invest to earn a return. With debt, that required return is explicit and takes the form of an interest rate, but with equity, there is scope for wishful thinking, since the bulk of the cost is implicit.
The Implausible
Market Dynamics Assume you are telling your story about a company that operates in a very competitive sector, and in your story, you see the company capturing a higher market share of this market. That is a plausible story, but not if you also claim that the company will be able to simultaneously raise prices on its products and have higher profit margins.
The Big Market Delusion In some cases, stories that are plausible at the individual-company level can become implausible in the aggregate. One classic example is what I term the big market delusion, in which companies notice a big market (China, the Cloud, ride sharing, online advertising) and are drawn to it by the opportunities they see.
the twist that causes the deviation from rationality and makes both the entrepreneurs and VCs overconfident, the former in the superiority of their products over the competition and the latter in their capacity to pick winners.
each business cluster (the entrepreneur and the VCs that back his or her business) will now overestimate its capacity to succeed and its probability of success, resulting in the following. First, the businesses targeting the big market will be collectively overvalued. Second, the marketplace will become more crowded and competitive over time, especially with new entrants being drawn in because of the overvaluations. Thus, while revenue growth in the aggregate may very well match expectations of the market being big, the revenue growth at individual firms will fall below expectations and operating margins will be lower than expected. Third, the aggregate valuation of the sector will eventually decline and some of the entrants will fold, but there will be a few winners, and those entrepreneurs and VCs will be well rewarded for their investments.
extent of the overpricing will vary, depending on the following factors:
1. The degree of overconfidence: The greater the overconfidence exhibited by entrepreneurs and investors in their own products and investment abilities, the greater the overpricing. While both groups are predisposed to overconfidence, that overconfidence tends to increase with success in the market. Not surprisingly, therefore, the longer a market boom lasts in a business space, the larger the overpricing will tend to get in that space.
2. The size of the market: As the target market gets bigger, it is far more likely that it will attract more entrants, and if you add in the overconfidence they bring to the game, the collective overpricing will increase.
3. Uncertainty: The more uncertainty there is about business models and the capacity to convert them into end revenues, the more overconfidence will skew the numbers, leading to greater overpricing in the market.
4. Winner-take-all markets: The overpricing will be much greater in markets in which there are global networking benefits (i.e., growth feeds on itself) and winners can walk away with dominant market shares. Since the payoff to success is greater in these markets, misestimating the probability of success will have a much bigger effect on value.
Every decade or so, this phenomenon of collective overpricing plays out in a young market—PC companies in the 1980s, dot-com companies in the 1990s, and social media companies in the last few years. Each time that overpricing is corrected, often characterized as the bubble bursting, the words “never again” are used by investors, regulators, and onlookers, suggesting that lessons have been learned that will prevent a reoccurrence of the cycle. I believe that as long as you have markets, this collective overpricing is a feature of markets—and not always an undesirable one.
The Improbable
what is it that makes a story improbable? It is not that you disagree with the storyteller’s views on revenue growth, profit margins, reinvestment, or risk, but that the storyteller’s views on these are internally inconsistent, that is, they are at war with one another.
The simplest device that I have for finding these inconsistencies is what I call the iron triangle of value (shown in figure 7.8).
The three corners of the triangle—growth, risk, and reinvestment—are the drivers of the value of a business,
As growth increases, value will go up, but as risk or reinvestment increases, value will go down.
Not surprisingly, a storyteller with an agenda of making a company more valuable will tell a story that combines high growth with low risk and low reinvestment, but that story is usually implausible because it is inconsistent.
A company with high growth will generally need to have high reinvestment to deliver that growth, and it will be riskier than average much of the time.
In my narrative for Ferrari, I assumed that it would strive to stay an exclusive club, not trying to increase production and units sold but preserving its limited reach and aiming for ultrarich clientele.
The upside in the narrative is that Ferrari will be able to preserve its high profit margins and reduce its exposure to macroeconomic risk, but the downside is that there will be low revenue growth.
Consider an alternative strategy that I will title the “rev it up” strategy. In this one, Ferrari expands its customer base, perhaps by introducing a lower-priced version; this would mirror what Maserati did with its Ghibli model. That will allow for higher revenue growth, but like Maserati, Ferrari will have to yield some of its operating margin, since this strategy will require lower prices and higher selling costs.
This is clearly a viable alternative strategy that passes the plausibility test.
For an example of an implausible narrative, you could argue that Ferrari will increase sales by introducing a new model, like Maserati has, but be able to maintain the margins it has had historically and not affect risk. That strategy yields a value-increasing combination of numbers (high revenue growth + high operating margin + low risk), but it is an implausible combination.
Finally, for an improbable narrative, you could spin the tale of Ferrari generating billions of dollars in revenues and profits from selling merchandise, including clothes, watches, and toys. While that narrative could happen, the probability of it unfolding seemed low, at least from my perspective in late 2015.
The intrinsic value is the value you would attach to an asset based upon its fundamentals: cash flows, expected growth, and risk. The essence of intrinsic value is that you can estimate it for a specific asset, without any information on how the market is pricing other assets
if you stay true to its principles, a DCF model is an intrinsic valuation model, because you are valuing an asset based upon its expected cash flows, adjusted for risk.
DCF valuation, the intrinsic value is estimated in an equation that ties value to expected cash flows, and these expected cash flows incorporate your estimates of growth and a discount rate that carries the weight of reflecting risk
One of the limitations of DCF valuation is that it is designed to value going concerns, that is, businesses you expect to stay operating for long periods, and that the value that you get will be too high if there is a significant chance the company will not make it.
This failure risk is high for young companies that have to make it through a gauntlet of tests to become operating businesses and for older, declining busineses that are overburdened with debt. In these cases, to estimate an expected value, you should consider the probability and consequences of failure for investors in the company explicitly, which leads to an adjusted value shown in figure 8.2.
if you think of cash flows as your endgame, you can start by first estimating revenues as the product of the total market that you see the company aiming at and the market share that you estimate it will be able to command within this market. Multiplying these revenues by the pretax operating margin yields the operating income of the company, and netting out taxes generates the after-tax operating income. Netting out what the company has to reinvest to generate growth will result in the free cash flow. Finally, discounting these cash flows back to today at a risk-adjusted discount rate gives you value.
If you have a big market story, it is the total market that will reflect it; even a small share of this market will generate big revenues. If you are pushing a strong networking benefit story, one that promises that your company will find it easier to grow as it gets larger, or a market dominance story, in which your company will overpower its competitors, the market share is the input that will allow you to incorporate this effect in value.
If the business you are valuing has strong and sustainable competitive advantages, you will see the payoff in high operating margins and income. If a business will benefit from tax breaks, the tax rate will be lower, pushing up after-tax income and cash flows. If your business is built on low capital intensity, that is, it can scale up easily, it is the reinvestment that will show that advantage, remaining low for big increases in revenues. If a business is low risk, the discount rate that you use to bring the cash flows back to today will be lower (and the value higher). Figure 8.3 summarizes the effects.
Qualitative Meets Quantitative The chasm between story people and numbers crunchers is most visible when the discussion turns to qualitative factors. To the storytellers, the obvious weakness of valuation models seems to be their failure to consider corporate culture, the quality of management and employees, and a multitude of soft factors that affect the value of a business. To the number crunchers, the raising of qualitative factors is a red flag, an indication of shallow thinking and the use of buzzwords to justify premiums. I find myself in the middle on this one, since I believe that both sides have a point.
there are many investors who feel that the intrinsic value process is too complex and that it is simpler and more effective to price companies, rather than value them. That pricing usually takes the form of computing a pricing multiple (of revenue drivers, revenues, earnings, or book value) and comparing this multiple across “comparable” firms.
value of a business is determined by the magnitude of its cash flows, the risk/uncertainty of these cash flows, and the expected level and efficiency of the growth that the business will deliver. The price of a traded asset (stock) is set by demand and supply, and while the value of the business may be one input into the process, it is one of many forces, and it may not even be the dominant force. The push and pull of the market (momentums, fads, and other pricing forces) and liquidity (or the lack thereof) can cause prices to have a dynamic entirely their own, which can lead to the market price being different from value.
To estimate value, as we noted in the previous section of this chapter, we use DCF models, make assumptions about the fundamentals that drive value, and estimate a value. To figure out a price, we take a much simpler path. We look at how “similar” assets are being priced in the market today and try to estimate a price that the market would attach to the company in question, given its characteristics.
3 steps in pricing:
1. Find comparable or similar assets in the market: While the conventional practice for doing relative valuation, at least in the context of stocks, is to look at other companies in the same sector as the company you are pricing, it is ultimately a subjective judgment and will depend largely on how investors in the market classify a company.
2. Look for the pricing metric that investors use in pricing these companies: When pricing companies, it is not your place or mine to determine what investors should be using to price companies, but what they actually are using. Thus, if the metric investors focus on when pricing social media companies is the number of users these companies have, you should focus on that metric in pricing your company.
3. Price your company: Now that you have the metric or metrics that investors are using to price companies, you can price your company based on that metric and the pricing ratios across the comparable companies.
The pricing process can yield a very different number for your company than the valuation process. As to which number you would use, it depends on whether you are an investor or a trader, with no negative connotations on the latter intended. Investors focus on value and invest on the faith that price will move toward value. Traders focus on price and are judged on whether they get the direction of price movements right.
Connecting Stories to Prices It is my view that most individuals in public markets, including many who call themselves value investors, are really traders, afraid to accept that labeling because they view it as a reflection of shallow analysis and are afraid of being called speculators. In the private capital markets, the delusion is even deeper, as most venture capitalists have little interest in value and are relentlessly focused on pricing. In fact, the venture capital (VC) valuation model is a pricing tool in which the pricing is consigned to the exit multiple,
Dangers of Pricing Stories
1. Intermediate variable: No matter what metric is used in the pricing, it is, at best, an intermediate step on the way to value or, at worst, a proxy for nothing substantial. Pricing a social media company on the basis of the number of users implicitly assumes that future revenues, earnings, and ultimately value are correlated with the number of users today. Even with more value-driven metrics like earnings, there is the assumption that earnings today are good indicators of future earnings, a dangerous leap of faith in unstable and volatile sectors.
2. Markets are fickle: If your defense is that it is your job to deliver what markets want (users, revenues, or earnings), it is worth remembering that markets are fickle. Young companies, particularly, will be faced with what I call “bar mitzvah” moments, where the market suddenly shifts its attention from one variable to an entirely different one.
3. Game playing by companies: If investors do become focused on a metric, companies will start to not only mold their stories around the metric but may start changing their business models to focus on delivering on that metric.
inputs are interconnected, that is, changes in one almost always trigger changes in the others. Thus, if you decide to increase the growth rate in a valuation, you have to consider how much your reinvestment will need to change to deliver that growth and whether you will have to alter your business mix (and the risk of that mix) and financial leverage to deliver that growth.
Thus, if you generate a return of 12 percent on the capital invested in new projects, you will need to reinvest 25 percent of your after-tax operating income in perpetuity to be able to grow at 3 percent a year. In fact, if the return on capital you generate is equal to your cost of capital, the terminal value will not change as growth changes, since growth becomes a neutral variable.
This not only allows you to keep terminal value constrained but also leads to a strong implication. The value added by your growth estimate in stable growth is a function of whether you believe that a firm can maintain its competitive advantages in the long term.
To get from the operating asset value to the value of equity in a business and from that equity to value of equity per share in a publicly traded company requires judgments on the following:
1. Debt and cash (net debt): In most valuations, the net debt is a minor and trivial detail at the end of the valuation, a number to be netted out from the value of operating assets to get to the value of equity. That does mask estimation issues with one or both of these numbers. With debt, the key question becomes what you would include in it, and the answer is that it should comprise not just the interest-bearing liabilities that you see on a company’s balance sheet but also other contractual commitments that the firm faces.
2. Cross holdings: It is not uncommon for a company to hold portions of other companies, and as an investor, you partake in these holdings. As a consequence, you have to bring the value of these holdings into your estimated value, and to do this, you first have to understand how the firm accounts for these holdings.
3. Stock-based compensation: In the last two decades, many companies have begun compensating their employees with equity in the company, either in the form of restricted shares (with restrictions on trading) or options. Since these are employee compensation, there is no conceivable argument for not treating them as operating expenses at the time that they are granted, even if that involves valuing the options using option pricing models.
Marginal return on capital = Change in operating income/Reinvestment
Can equity have a negative value? The answer is no and yes: no, because the market price cannot drop below zero, and yes, because a company can sometimes continue in existence, even in this diseased state, buoyed by hope that a turnaround can bring up the value of the operating assets. In these cases, equity takes on the characteristics of an option, and investors should treat it as such.
can you reverse the process? In other words, can you take a DCF valuation, which is all numbers, and back out a story from those numbers? Yes, and there are reasons that you might want to do so.
First, once you extract the story from the numbers, you can assess whether it is a story with which you are comfortable. After all, it is not just the numbers that should be driving your investment decision when you are looking at a company, but the story behind the numbers. Second, you can use your backed-out narrative to question the person doing the valuation about the underlying assumptions. One test of whether an analyst is mechanically plugging numbers into models or has a serious story will come out in how he or she responds to your questions.
Improving and Modifying Your Narrative—The Feedback Loop
your narrative is not the only plausible one and that there might be alternative stories for the same business. Rather than dismiss these alternative narratives as wrong and defend your own, you will be better served if you keep the feedback loop open and consider whether any of these alternative narratives have parts that you may want to borrow or adapt to make your own better.
these changes may be because others know more about the company being valued and the business it operates in than you do, and their alternative tales may reflect this knowledge. In other cases, these changes may just reflect an admission on your part that your original story was flawed.
Fighting Hubris Hubris is a good place to start this chapter, because it lies at the root of so much investing pain. It is natural to feel pride and ownership in a narrative that you, as founder or investor, have developed for a company, and it is almost as natural to feel the urge to not only defend it against criticism but to stay bound to it.
two actions that open me up for change. The first is to tell my story to the groups that are least likely to like that story and allow them to air their disagreements. The second is to be open about the uncertainty that I feel in my own story and how it plays out in the resulting estimates and value.
Get Out of the Echo Chamber
the story for your company is that of a high-flying tech start-up, telling that story to a group of entrepreneurs and venture capitalists will get heads nodding in agreement and consensus about your superior storytelling abilities. If you try that story out in front of a group of old-time value investors, you will find yourself quickly in the firing line, having to defend almost every part of your story.
be open about tenets in investing and valuation that you think are truths, but are just beliefs. Thus, while growth may always be a “good” in a gathering of venture capitalists, it will be greeted more skeptically in the value investor conferences. To explain why growth is good, you have to then think about how growth affects value, and why growth can sometimes destroy value.
in the process of trying to explain why growth is good to value investors, you may discover that you have perhaps not done your homework or have made an assumption that is either wrong or not well thought through.
Face Up to Uncertainty
As you get further and further into the number crunching, there will be a point in time where you will start thinking of these estimates as facts and your value estimate as the truth.
The antidote to this false precision is the recognition that your valuation is based on “point estimates”—your base case values for expected growth, margins, and cost of capital—and each of these numbers comes from a probability distribution.
It is a good idea to be more explicit about this uncertainty that you face, and there are four techniques you can use:
1. What-if analysis: In what-if analysis, you take individual variables in your valuation and vary them, keeping all other inputs fixed. In the Amazon valuation, for instance, I could estimate the value for Amazon for growth rates ranging from 10 to 20 percent. Why do this? The first is to see how much changing a variable affects value and using that knowledge to decide whether you should collect more information about that variable before your investment decision.
2. Scenario analysis: In scenario analysis, you allow all or many of the variables in your analysis to change across scenarios, and you value your business in each scenario. In its most useless form, the scenarios are defined as best, base, and worst-case scenarios, with the unsurprising results that your business is worth a lot in the best case, nothing or very little in the worst case, and an intermediate amount in the base case.
3. Decision trees: Decision trees are probabilistic tools designed to evaluate discrete and sequential risks in a business. Thus, they are well suited for evaluating companies that need regulatory approval to operate or pharmaceutical/biotech companies that have to go through multiple stages of the drug approval process. Being forced to examine the sequential events that your company has to go through to get to success makes you think more deeply about weak links in your story.
4. Simulations: A simulation is the fullest and
richest way of assessing the effect of uncertainty. Unlike a what-if analysis, in which you are restricted to changing only one variable at a time, you can change as many of your input variables as you want, and unlike a scenario analysis, in which you have to break down the future into specific scenarios, simulations allow you to examine a continuum of possibilities. In fact, a version of simulation will even allow you to incorporate decision trees and binding constraints into the simulation; a bank that violates a regulatory capital bound or a debt-laden company that is unable to meet a contractual commitment can be put out of business.
There is nothing more disconcerting than valuing a company and arriving at an estimate that is wildly different from the current price. I know that is why we value companies, i.e., to find market mistakes, but when there is a wide divergence, there are four possible explanations.
The first is that you are right and that the market is wrong. The second is that you are wrong and that the market is right. The third is that both you and the market are wrong, because the intrinsic value is an unknowable number. The final possibility is that the pricing and value processes, described and contrasted in chapter 8, have diverged and that the market is pricing companies, whereas you are valuing them.
The third explanation is the one that I start with, since it requires me to accept the possibility that I am wrong in my narrative and, as a consequence, in my value. It then stands to reason that no matter how comfortable I am with my story, I should try to at least gauge what the market is expecting and then compare those expectations to mine, not necessarily with the intent of changing my estimate but as a precursor to doing more research and perhaps making a better decision.
If, after looking at the possibilities, I am still comfortable with my narrative, I conclude that the pricing and value processes have diverged, resulting in a gap between the two. Whether I am willing to put real money on the gap will depend on whether I have faith, first in my own story and resulting value, and the other in the gap closing within my prescribed time horizon.
the persistence of Amazon’s price climb suggested to me that investors were not valuing Amazon but pricing it and that they were therefore likely to be impervious at least in the near term to fundamentals. That is also why, notwithstanding my assessment that Amazon was overvalued, I did not take the obvious next step and sell short on the stock. Cowardly on my part? Of course, but I think it would have been foolhardy for me to take a position based upon intrinsic value on a pricing stock, if I did not control my time horizon, and in the case of a short sale, I did not.
1. Make your narrative and valuation transparent: It is difficult to get criticism that you can use to improve your valuation, if you do not reveal the details of your valuation or the story behind the numbers.
2. Have an open forum for people to comment on your valuation: If you claim to welcome criticism, you have to make it easier for people to criticize you, not more difficult. To me, this is one of the advantages of presenting my valuations online, as I have on my blog for the last few years.
3. Separate the constructive criticism from the noise:
4. Use the narrative to organize the criticism: Having a clear narrative with parts to it helps me organize the feedback that I get from those who disagree with me. Thus, I can break down disagreements into those about my estimate of the total market, my judgments about market share and operating margins, and my evaluation of risk in a business.
5. Look for the weakest links: If I find particular parts of my narrative are attracting more negative feedback and disagreement than others, it is a signal to me that I have either not been clear about explaining my reasoning or, worse, that I have not fully thought through that part of my story.
I find that the more uncertainty there is around a company, the more open I have to be to alternative story lines.
Narrative Alterations—The Real World Intrudes
but if the real world changes, your narrative, to stay realistic, has to change as well.
If the only constant in business is change, and the pace of change is increasing with technology and globalization, it stands to reason that no narrative can stay unchanged for a long period. It is prudent to respond to new developments and information by revisiting your narrative and evaluating whether any parts of it may need to be changed.
1. Qualitative versus quantitative: The news can be quantitative, ranging from the surprises in earnings reports to government reports on inflation and economic growth.
qualitative, some examples being a change in top management, a legal judgment for or against the firm, or the announcement that an activist investor has taken a position in the company.
qualitative, some examples being a change in top management, a legal judgment for or against the firm, or the announcement that an activist investor has taken a position in the company. 2. Inside versus outside: The information can sometimes be from the company in the form of either a required financial disclosure or as a corporate announcement (of an acquisition, divestiture, or a buyback) and sometimes from external sources (financial news, equity research analysts following the company, or regulatory authorities). In some cases it may even be from a competitor, with the information that you get changing the way you think about the market and competitive dynamics.
3. Micro versus macro: Much of the information that you get is at the micro level, that is, it is about the company, its competitors, or the sector. Some of the news that you get will be about macroeconomic factors, that is, shifts in interest rates, exchange rates, or inflation can alter your story.
The view promoted by some old-time value investors that intrinsic valuation is timeless and constant is not only wrong but can be dangerous to portfolio health.
Narrative Breaks
1. Natural or man-made disasters:
2. Legal or regulatory action:
3. Failure to make contractual payments:
4. Government expropriation: While expropriation by the government is less common than a few decades ago, there are still parts of the world where a business can be taken over without the owners receiving fair compensation.
5. Capital squeeze: Many ongoing businesses need capital not just for expansion but for day-to-day operations, and a market crisis that shuts down access to capital could cause these businesses to fold.
6. Acquisition: In perhaps one of the few instances of an unexpected narrative end that is good news, a company can be acquired and become part of a much larger entity.
When you make these changes, though, recognize that you will have to explain what parts of the story you have changed and why, and also be ready for criticism from two sources:
- The value scolds: Coming from a belief system that intrinsic value is a stable, perhaps even constant number and that big changes in it are an indication of weakness, value purists will pounce on your changes and argue that this is more a sign that your original valuation was flawed than a sensible adjustment to new information.
- The hindsight gurus: There will be another group of critics who will take you to task for not having the foresight to see the changes that you have made coming at the time of your original valuation.
The Big Stories The macro variables that you can build corporate stories around are many, but the three that are most used are commodity, cyclicality, and country. In the first (commodity), you build a story around a commodity-driven company, with the commodity price being the central variable and the company’s expected response to commodity price changes determining value. In the second (cyclicality), the valuation is of a company, and the primary driver of operating numbers is the overall health or lack thereof of the economy. Thus, your story starts with the economy, with the company woven into it, and requires that you link your company’s prospects to how well or badly the economy does. In the third (country), the driver of value for the company is the country in which it is incorporated and where much of its operations are centered,
In my experience, there is no aspect of investing that has a worse track record than investment strategies based on macroeconomic forecasting. With commodities, you would be hard-pressed to find a single commodity price reversal (where a commodity on the downside reversed course and starting rising or a rising commodity price started its decline) in the last fifty years that analyst consensus saw coming.